
 salehunter.net
American consumers are constantly navigating a complex financial landscape. With the cost of everyday essentials fluctuating at the grocery store, the gas pump, and everywhere in between, finding ways to stretch a dollar has never been more critical. The classic solution used to be extreme couponing—a process that required hours of dedication, scissors, Sunday newspapers, and a heavily organized binder. Today, however, that entire arduous process has been streamlined into a seamless digital experience. A single rewards app download can fundamentally shift how you manage your discretionary income, turning standard errands into opportunities for financial return.
But navigating the App Store or Google Play Store can feel incredibly overwhelming. There are hundreds of applications out there, each promising free gift cards, instant cash back, and exclusive digital discounts. How do you separate the genuinely lucrative platforms from the digital clutter that only drains your battery? The secret lies in treating your smartphone real estate like a strategic financial portfolio. You do not need fifty different applications; you only need a highly curated selection that fits your natural spending habits.
Understanding the Mechanics: Why Are They Paying You?
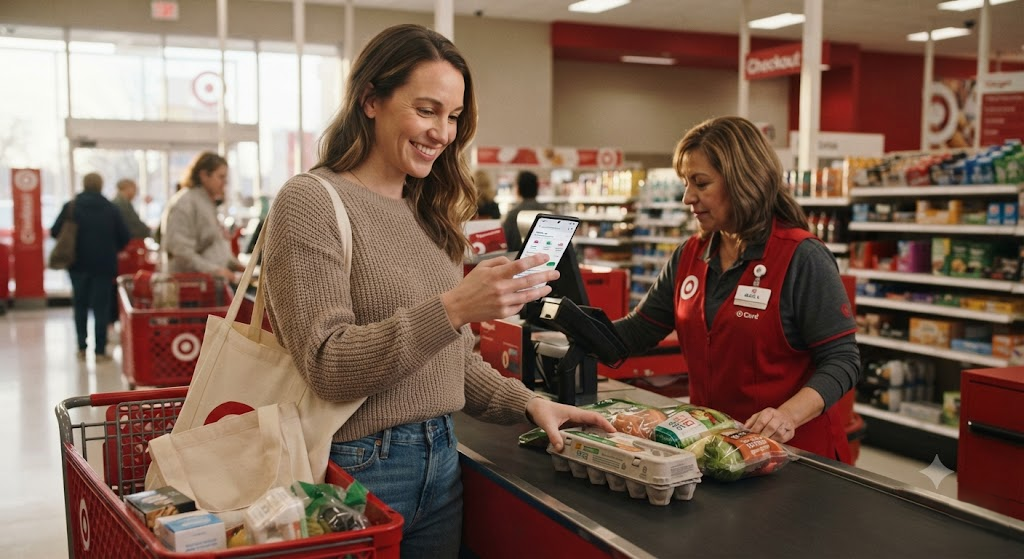
When an application promises you free money for doing something you were already going to do—like buying groceries, picking up a prescription, or pumping gas—it is entirely natural to be skeptical. The immediate thought is often to look for the catch. Understanding the business model behind these platforms is the first step to becoming a smarter, safer consumer.
Brands and massive retail corporations dedicate billions of dollars annually to marketing and customer acquisition. Instead of spending all that budget on traditional television commercials or easily ignored internet banner advertisements, they partner directly with rewards applications. When you execute a rewards app download, you are essentially stepping into a highly targeted, performance-based advertising ecosystem. For example, if a company wants to incentivize consumers to try a newly released flavor of sparkling water, they will offer a one-dollar rebate through a cash-back platform. The app takes a small cut of the brand’s marketing budget for facilitating the transaction, and you receive the rest of the profit.
Furthermore, these tech companies aggregate anonymized consumer purchasing data. Market research firms are desperate to know granular details about shopping habits—like whether consumers who buy organic peanut butter also tend to buy premium paper towels. By uploading your receipts, you are contributing to a massive, anonymized database of consumer behavior. In the modern digital economy, your data and your attention are incredibly valuable commodities. These apps simply represent a way for you to finally get a cut of that transaction.
The Essential Portfolio: Categories of Apps You Need
Not all cash-back platforms function in the same way. To truly maximize your return on investment, you need a diversified approach. Here is a detailed breakdown of the specific categories you should consider when planning your next rewards app download.
- Receipt Scanning Applications: This is arguably the most interactive and popular category. Platforms like Fetch Rewards or Ibotta require you to physically scan a paper receipt using your phone’s camera or to link a digital retailer account. Fetch operates on a highly gamified points system where every single receipt, regardless of what you actually purchased, earns you baseline points. Buying specific partner brands yields massive point multipliers. Ibotta requires a bit more active planning; you generally need to browse and select the specific item offers you want before you reach the checkout counter. The payout, however, is often direct cash to your bank rather than just points for gift cards.
- Card-Linking Technology: For those who prefer a completely passive “set it and forget it” approach, card-linked apps are the ultimate tool. Applications like Dosh allow you to securely link your everyday credit or debit card directly to your user profile. When you swipe that specific card at a participating local restaurant or national retailer, the system automatically recognizes the transaction and credits your account. There are no paper receipts to scan and no digital barcodes to present to a cashier. The savings happen entirely in the background.
- Category-Specific Platforms: Some of the most lucrative savings come from highly specialized applications. Upside, for instance, was specifically designed to help Americans combat volatile fuel prices. By opening the map interface before you pull into a gas station, you can claim a per-gallon rebate that quickly adds up over a month of commuting. While they have expanded into the restaurant and grocery sectors, gas remains their standout feature. If you drive frequently, a specialized fuel app is a non-negotiable download.
- Browser Extensions and Online Portals: While commonly associated with desktop computers, platforms like Rakuten have incredibly powerful mobile applications. If you are doing any online shopping on your phone—whether you are ordering a new winter coat or booking a hotel room—you should be routing that purchase through a cash-back portal. They earn an affiliate commission for directing your web traffic to the retailer, and they generously split that commission with you.
The Advanced Strategy: Mastering the Art of App Stacking
Executing a single rewards app download is a great start, but downloading several complimentary apps and making them work in tandem is how you generate significant passive savings. This concept is known in the deal-hunting and financial independence communities as “stacking.” Because these different applications operate independently of one another, they rarely restrict you from claiming rewards on the exact same purchase across multiple platforms.
Let’s look at a practical, everyday example. Imagine you need to buy a specific brand of premium laundry detergent that retails for $12. First, you check your credit card’s native rewards program to ensure you are using a card that naturally gives you 2% cash back on grocery purchases. Second, you see that the detergent happens to be on sale at your local store for $10. Third, you open an app like Ibotta and find a $3 cash-back offer specifically for that item. After you make the purchase, you scan the physical receipt into Fetch Rewards to earn your baseline points. Finally, you scan that exact same receipt into yet another general app like Receipt Hog.
By effectively stacking a standard store sale, a credit card reward, an item-specific rebate, and two general receipt-scanning bonuses, you have successfully slashed the real price of that detergent in half. The secret to successful stacking is organization. You do not want to hold up the checkout line fiddling with five different mobile apps. The most successful users spend ten minutes on Sunday morning reviewing their platforms, clipping digital offers, and writing their physical grocery lists accordingly.
Protecting Your Digital Footprint: Privacy and Security
A very real barrier that prevents many people from initiating a rewards app download is the fear of data breaches or privacy violations. These are incredibly valid concerns. You are handing over detailed, granular information about your purchasing habits, and in some cases, linking your highly sensitive financial institutions. To safely navigate this space, you must employ strict digital hygiene.
First, scrutinize the app permissions immediately upon installation. Does a simple receipt-scanning app actually need 24/7 access to your precise GPS location? Almost certainly not. You can manually adjust these settings in your phone’s privacy menu, granting location access only while the app is actively in use. Second, be incredibly selective about which bank accounts you choose to link. Reputable cash-back apps use secure, third-party financial integrators like Plaid. Plaid acts as an encrypted intermediary; the rewards app never actually sees your bank login credentials or passwords, only the basic transaction data necessary to award you points. If an obscure, unreviewed app asks you to manually type your bank password into their own proprietary interface, immediately delete the application.
Finally, consider creating a dedicated email address strictly for your digital savings accounts. Many platforms offer substantial point bonuses for linking your email so they can automatically scan your inbox for digital e-receipts from companies like Amazon, Target, or Instacart. Providing a dedicated “shopping only” email address protects your primary personal or professional inbox from potential data mining and the inevitable, daily influx of promotional newsletters.
Common Pitfalls and How to Avoid Them
While the financial upside is substantial, the digital rebate landscape is intentionally littered with psychological traps designed to benefit the corporation rather than the consumer. The most prevalent trap is induced spending. It is incredibly easy to fall into the mindset of purchasing a $6 box of premium snacks you don’t even like just because there is a $2 rebate attached to it in your app. You must remember the golden rule of deal hunting: if you would not have purchased the item at full price without the app, buying it solely for a rebate is not saving money; it is spending money unnecessarily.
Another incredibly common consumer frustration is the minimum payout threshold. Many applications require you to accumulate $20 or even $25 worth of points before you can transfer the funds to your PayPal account or redeem a digital gift card. Companies do this intentionally, knowing a certain percentage of users will lose interest and abandon the app at $12, effectively leaving that money locked in the company’s own pockets. Before you commit your time and data to a new platform, always check the payout minimum in the terms of service. If you are only a casual, occasional shopper, a high payout threshold might take you an entire calendar year to reach.
Lastly, pay close attention to point expiration policies. Extended periods of user inactivity can sometimes completely wipe out your hard-earned balance. A simple strategy is to set a recurring calendar reminder on your phone to log in and engage with your top downloaded apps at least once a month, ensuring your accounts remain active and in good standing.
Evaluating the App Store Listing Before You Commit
With new platforms launching seemingly every week, you need to know how to vet an application before you tap that download button. Do not just look at the overall star rating, as those can sometimes be manipulated. Instead, dive into the written reviews and sort them by the most recent. Are users complaining that the app suddenly crashes when they try to cash out? Are there reports of customer service ignoring missing cash-back claims? These are massive red flags.
Additionally, look at the developer’s history. Is this their only app, or are they a known entity in the financial technology space? Legitimate rewards platforms have transparent privacy policies easily accessible from their store listing. If an app makes it incredibly difficult to figure out how they use your data, take your business—and your receipts—elsewhere.
The Future of Consumer Incentives
The landscape of consumer rewards is evolving at a breakneck pace. We are steadily moving away from blanket, generic discounts and toward hyper-personalized offers driven by sophisticated artificial intelligence. In the near future, your rewards app download won’t just offer you a static list of rebates. The algorithm will actively analyze your historical purchasing data and dynamically generate unique offers tailored precisely to your exact habits, potentially offering you larger, custom rebates to entice you to switch from your favorite brand to a competitor.
We are also seeing the slow integration of alternative payout methods. While PayPal and Amazon gift cards remain the standard, some forward-thinking platforms are allowing users to redeem their cash back for fractional shares of stock or even cryptocurrency. This shift is effectively turning everyday grocery shopping into an automated micro-investing strategy, allowing consumers to build long-term wealth simply by buying their weekly essentials.
Final Thoughts on Your Digital Strategy
Adopting a strategic, informed approach to digital savings does not require a massive time commitment or an advanced degree in finance. By carefully selecting a few highly reputable platforms, understanding the underlying mechanics of how these companies monetize your data, safely stacking multiple offers across different ecosystems, and rigorously avoiding the psychological temptation to overspend, you can easily reclaim hundreds of dollars a year. That next simple rewards app download could very well be the most efficient, lowest-effort side hustle you ever start, putting real money back into your pocket where it belongs.